

Dollar Thrifty Automotive Group Reports Record 4th Quarter Profit
Dollar Thrifty Automotive Group realized a $69.6 million year-over-year improvement in Corporate Adjusted EBITDA for the fourth quarter of 2009 after four consecutive quarters of year-over-year improvement in financial performance.
Dollar Thrifty Automotive Group, Inc. today reported results for the fourth quarter and year ended Dec. 31, 2009. Net income for the 2009 fourth quarter was $11.5 million, or $0.42 per diluted share, compared to a net loss of $72.2 million, or $3.36 loss per diluted share, in the fourth quarter of 2008. Net income for the fourth quarter of 2009 included a favorable impact on income of $0.14 per diluted share, compared to a loss of $1.54 per diluted share in last year's fourth quarter, both of which relate to changes in fair value of derivatives and impairments of long-lived assets.
Non-GAAP net income for the 2009 fourth quarter was $7.7 million, or $0.28 per diluted share, compared to a non-GAAP net loss of $39.1 million, or $1.82 loss per diluted share, for the 2008 fourth quarter. Non-GAAP net income (loss) excludes the (increase) decrease in fair value of derivatives and non-cash charges related to the impairments of long-lived assets, net of related tax impact. Corporate Adjusted EBITDA for the fourth quarter of 2009 was $26.2 million, compared to a loss of $43.4 million in the fourth quarter of 2008. "We are all proud of the company's dramatic financial turnaround that is clearly demonstrated in our operating results for the quarter and full year. The company realized a $69.6 million year-over-year improvement in Corporate Adjusted EBITDA for the fourth quarter. Additionally, we also are reporting our fourth consecutive quarter of year-over-year improvement in financial performance while operating in the challenging economy of 2009," said Scott L. Thompson, president and CEO.
For the quarter ended Dec. 31, 2009, the company's total revenue was $345.3 million, as compared to $355.1 million for the comparable 2008 period. The decline in revenue was primarily driven by a 12.2 percent decrease in rental days, partially mitigated by an 11.6 percent improvement in revenue per day. On a same store basis, rental revenues for locations open during both periods were up 1.7 percent compared to the fourth quarter of 2008. The fourth quarter average fleet was down 10.5 percent compared to the fourth quarter of 2008.
"Revenue for the quarter was in line with our expectations and our overall return on asset strategy. We continue to focus on the profitability of rental transactions and overall price discipline in the industry. Consistent with our strategy, at times we will accept lower transaction days and utilization in order to maintain the proper balance between price and volume," said Thompson.
Per vehicle depreciation cost of $274 per month in the fourth quarter of 2009 was approximately 33 percent lower than the comparable quarter of 2008. Numerous factors drove the improvement in depreciation cost per vehicle, including a significant improvement in used vehicle residual values as they recovered from the historical lows experienced in the fourth quarter of 2008, extension of our fleet holding periods, better mix optimization, a move towards a greater proportion of risk vehicles in the fleet and more effective remarketing. Vehicle utilization was 78.8 percent, down 150 basis points from last year's fourth quarter. Utilization was adversely impacted by an increase in the number of vehicles held for remarketing during the period and the company's focus on price discipline.
Direct vehicle and operating expenses and selling, general and administrative expenses were lower in the fourth quarter of 2009 compared to the same quarter in 2008 primarily as a result of transaction declines, cost reduction efforts and cost efficiency initiatives. As a percentage of revenues, these operating expenses declined 620 basis points to 65.1 percent of revenues, compared to 71.3 percent in the fourth quarter of 2008. Interest expense for the fourth quarter of 2009 declined on a year-over-year basis primarily as a result of a $760 million reduction in debt compared to 2008 levels, partially offset by lower returns on invested cash.
Full Year Results
For the year ended Dec. 31, 2009, net income was $45.0 million, or $1.88 per diluted share. For the year ended Dec. 31, 2008, the net loss was $346.7 million, or $16.22 loss per diluted share. The net loss in 2008 included a $14.31 loss per diluted share related to the impairment of goodwill and long-lived assets and changes in fair value of derivatives, compared to a favorable impact on income of $0.65 per diluted share in 2009. Consistent with our 2009 revenue guidance, total revenue for the year was $1.55 billion, a decrease of 8.9 percent over the comparable period in 2008.
Non-GAAP earnings per diluted share for the year ended Dec. 31, 2009 was $1.24, compared to a non-GAAP loss per diluted share of $1.91 for the same period in 2008. Non-GAAP net income (loss) excludes the (increase) decrease in fair value of derivatives and the non-cash charges related to the impairment of goodwill and long-lived assets, net of related tax impact. Corporate Adjusted EBITDA for the year ended Dec. 31, 2009 was $99.4 million, an increase of $101.7 million from the $2.3 million loss for the year ended Dec. 31, 2008. A reconciliation of non-GAAP to GAAP results is included in Tables 3 and 4.
"As we began 2009, we faced a number of significant challenges that necessitated changing the company rapidly in order to enhance our competitiveness and to properly position the company for success. I would like to thank the entire Dollar Thrifty team for their openness to change and their significant contributions in a difficult year," said Thompson.
Liquidity and Capital Resources
During the fourth quarter of 2009, the company further strengthened its liquidity and tangible net worth through a successful $120 million equity offering. As of Dec. 31, 2009, the company had $500 million in cash and cash equivalents, and an additional $623 million in restricted cash and investments primarily available for the purchase of vehicles and/or repayment of vehicle financing obligations. The company's tangible net worth at Dec. 31, 2009 was $368 million.
2010 Outlook
The company expects industry conditions to improve slightly in 2010 as a result of several factors. Continued improvement in the overall economy, combined with ongoing recovery in the credit markets, is expected to result in low single-digit growth in transaction days in 2010. The company believes that customer demand for its value-oriented leisure brands and continued industry pricing discipline will result in moderate price increases in revenue per day on a year-over-year basis. Finally, the company believes that recent favorable trends in the used vehicle markets will continue throughout 2010, resulting in solid residual values and improvements in monthly fleet operating costs year-over-year.
Based on the above expectations, the company is targeting Corporate Adjusted EBITDA for the full year of 2010 to be within a range of $120 million to $140 million. The Company provided the following additional information with respect to its full year guidance:
Vehicle rental revenues are projected to be up 2 – 4 percent compared to 2009, resulting from low single-digit increases in both transaction days and revenue per day.
Vehicle depreciation costs for the full year of 2010 are expected to be approximately $325 per vehicle per month. The company noted that disposition of vehicles is expected to create some volatility in the level of these costs on a quarter-to-quarter basis.
"In 2009, our primary objectives were the preservation of liquidity and maximization of cash flow. With those objectives achieved, the company is well positioned to take advantage of a mildly improving economy. We will seek profitable transaction growth in 2010 with the objective of maximizing return on assets for our shareholders," said
More Rental Operations
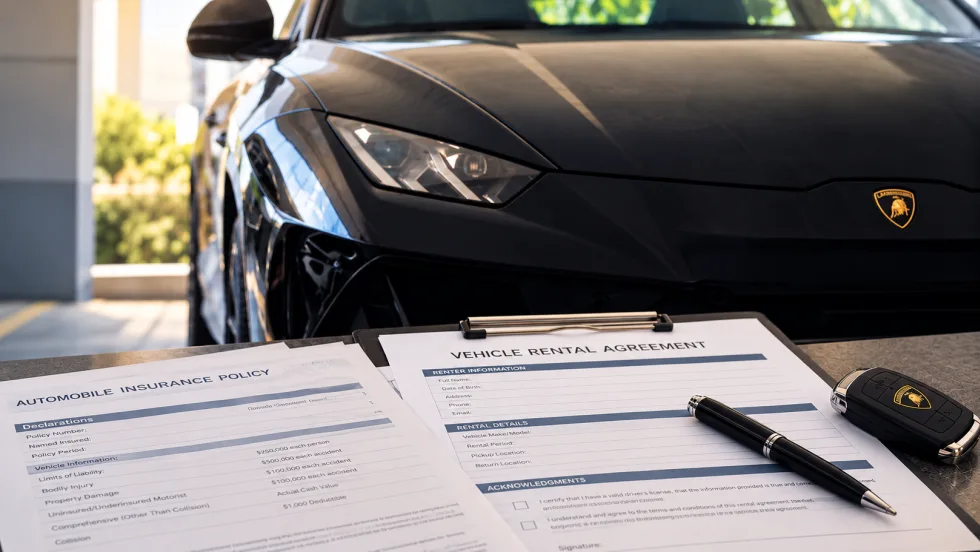
Clean on Paper: Red Flags in Exotic Car Rental Verification
A suspicious $45,000 Lamborghini booking reveals the strengths and limitations of renter verification, from forged insurance documents to coverage gaps and unauthorized drivers. (Part 2 of 3)
Read More →
Turo and Tesla Take the Next Step Toward Autonomous Car Rentals
The partnership brings Tesla's Full Self-Driving (Supervised) technology into the rental experience, offering a glimpse of how increasingly automated vehicles could change car rental.
Read More →
How Rental Operators Can Navigate Personalized Pricing Rules
As regulators scrutinize the use of customer data in pricing, rental operators need to know whether they can explain why one renter pays more than another.
Read More →
Direct, Broker or Hybrid? How Travel Retailers Source Rental Cars
As travel retailers weigh direct supplier relationships against third-party distribution, rental operators need to understand how those decisions affect their business.
Read More →
How Did This Independent Rental Operator Grow to 170 Vehicles in 4 Years?
With 170 vehicles across three Kentucky locations, Joel Price relies on an overseas team to handle reservations, payments, and after-hours customer service. It's one part of an unconventional approach to growing an independent rental operation.
Read More →
What Does It Take to Succeed in B2B Rentals?
The fundamentals may be familiar to daily car rental operators, but project-based truck rentals put different demands on the fleet and the business.
Read More →
NPR Builds on International Partnerships to Grow Rental Bookings
With Ana Laborde supporting broker development, NPR Auto Group is tailoring distribution strategies, rate packages, and partnerships to grow international reservations across its three brands.
Read More →
Advantage, Sixt Place Among Top Five in Annual Satisfaction Study
While Enterprise and National retain the top spots in JD Power’s 2026 rankings, the latest customer satisfaction results suggest renters can find competitive service beyond the biggest car rental names.
Read More →
The $100,000 Insurance Trap in Exotic Car Rentals
Exotic rental agencies often rely on customers’ personal auto policies to protect six-figure vehicles. But policy language can dramatically change the coverage for vehicles over $100,000 MSRP.
Read More →
The Booking Is Confirmed, But Is Your Customer Ready to Drive?
For international renters, a confirmed reservation doesn’t always mean they’re eligible to drive. Earlier checks can help operators catch documentation and payment issues before the customer reaches the counter.
Read More →