No Need for LKE Programs in 2011?
Tax consultant maintains that due to the recently signed tax relief law allowing for 100-percent bonus depreciation in 2011, like-kind exchange programs will have no benefit.
Ronald L. Hodgeman, Esq., a tax director for WTP Exchange LLC, has provided tax consulting and LKE Program implementation services to numerous companies, including banks, rental car companies, leasing companies and heavy equipment dealers. Hodgeman maintains that due to the recently signed tax relief law allowing for 100-percent bonus depreciation in 2011, like-kind exchange programs will have no benefit.
Now that 2011 is here, are you still looking for a New Year's resolution? How about this one - "I will not pay for something that I will not use in 2011"? Remember the gym membership that you haven't used since 2008? Cancel it. Are you paying $20 per month for Netflix but haven't watched a movie in eight months? It's time to unsubscribe. Is your company running a Like-Kind Exchange (LKE) program? Turn it off.
Yes, you read that correctly. If you are one of the hundreds of companies that have implemented an LKE program over the last 15 years, it might be time to turn off the program. Why? Because most companies will temporarily receive no benefit from an LKE program but there is still a significant cost to keeping one turned on. On December 17, 2010, President Obama signed into law HR 4853, the Tax Relief, Unemployment Insurance Reauthorization, and Job Creation Act of 2010 (the "Act"). One of the provisions included in the Act allows for 100 percent bonus depreciation in 2011.(1) In other words, for this current year, the Act lets taxpayers write off capital expenses right now, without having to adhere to the regular depreciation schedule. Temporarily, at least, this means that there is no benefit from your LKE program.
The following example illustrates why the 100 percent bonus depreciation eliminates the need for an LKE program:
§ Company ABC sells a fleet of vehicles in April 2011 for $6,000,000;
§ The vehicles are fully depreciated for tax purposes; and
§ Company ABC purchases new vehicles in July 2011 for $6,000,000.
2011 Tax Consequences - LKE Program | "Turned On" | "Turned Off" |
Gained Recognized Upon Sale | $0 | $6 million |
Less: Tax Depreciation | $0 | $6 million |
Total Tax Gain | $0 | $0 |
As you can see, the tax consequences are the same regardless of whether the sale and purchase transactions are part of an LKE program. The difference between the two scenarios is the cost of participating in an LKE program. The fees paid to the LKE software provider and Qualified Intermediary (QI) are often in the hundreds of thousands of dollars, and sometimes more. Do you really want to pay your LKE software provider all that money to simply calculate depreciation? And if I'm the CFO or treasurer, I'd much rather have the cash from the asset sales directed to my company's operating account rather than the QI account.
Don't get me wrong. During "normal" times, there is a tremendous benefit to be derived from an LKE program. An LKE program is powerful tax strategy that has allowed hundreds of companies to increase their cash flow by deferring the tax gain realized on the sales of their business assets. The majority of the rental car companies, equipment dealers, and leasing companies have implemented an LKE program. The strategy is even supported by a 2003 IRS Revenue Procedure that provides taxpayers with an array of safe harbors.
But these are not normal times. The money that your company saves by temporarily turning off the LKE program can be used to prevent the next round of layoffs, hire a new employee, or make capital expenditures.
Turning off an LKE program this year means taxpayers can also re-evaluate their current LKE providers and shop around for a better one, without having to worry that making a change midstream will result in a loss of tax deferral. Additionally, many companies are concerned about the security of their exchange funds and feel that there must be a better QI solution. Some may want better service from their LKE software provider or simply need better LKE software. Whatever the reason, now is a chance for organizations to review their LKE programs and do what is best for business.
If your company has not implemented an LKE program yet, now is the time to begin internal discussions around it. The 100 percent bonus depreciation can substantially reduce a company's taxable income in 2011. However, the bonus depreciation taken in 2011 will result in less depreciation deductions and more tax gain realized in future years - unless your company is ready to take advantage of an LKE program at that time. The message is simple ... turn off your LKE program now, but be ready to turn it on at the right time.
(1.) It is important to note that the 100% bonus depreciation provision is retroactive to September 9, 2010.
More Rental Operations
The $100,000 Insurance Trap in Exotic Car Rentals
Exotic rental agencies often rely on customers’ personal auto policies to protect six-figure vehicles. But policy language can dramatically change the coverage for vehicles over $100,000 MSRP.
Read More →
The Booking Is Confirmed, But Is Your Customer Ready to Drive?
For international renters, a confirmed reservation doesn’t always mean they’re eligible to drive. Earlier checks can help operators catch documentation and payment issues before the customer reaches the counter.
Read More →
ICRS 2027 Opens Call for Papers
The International Car Rental Show seeks session proposals on the business, operational, and technology issues facing car rental operators. Submissions are due Jan. 15.
Read More →
Turo to Launch Vehicle Delivery Service
Turo Delivered will let travelers search for vehicles that hosts can deliver directly to hotels, homes, airports, train stations, and other locations.
Read More →
Palm Beach Airport Code Change Creates Car Rental Distribution Gap
A test of rental searches under the old PBI and new DJT airport codes returned largely different sets of brands and vehicles, highlighting a potential distribution problem for rental operators.
Read More →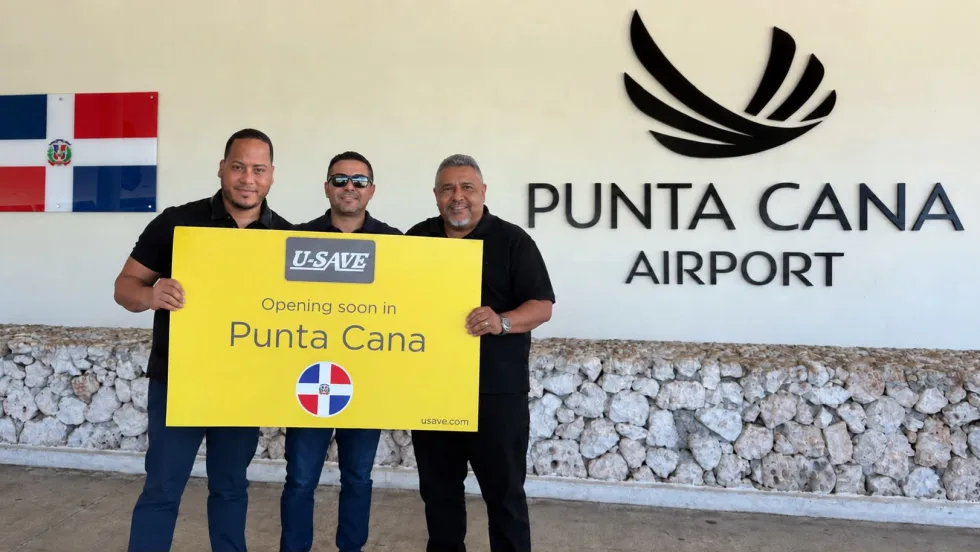
U-Save Continues Dominican Republic Expansion with Launch in Punta Cana
The new franchise location builds on U-Save’s existing Santo Domingo operation and will begin taking reservations for October 2026.
Read More →
When AI Books the Rental Car, Who Controls the Sale?
As AI moves from comparing rental rates to completing transactions, operators need to understand how travelers find, interpret, rank, and ultimately see their offers. (Part 2 of 2.)
Read More →
European Booked Car Rental Rates Fell 5%, Results Varied by Country
Ireland, Cyprus, and the United Kingdom saw steep declines, while booked rates rose in Poland and Hungary.
Read More →
Is It Time to Rethink Rental Categories?
As traditional economy and compact cars disappear from the market, longtime rental operator Mike DeLorenzo asks whether the industry’s familiar vehicle categories still make sense — and what operators need to rethink along with them.
Read More →
Who Owns the Rate? AI Is Creating a New Distribution Problem for Car Rental
Generative Engine Optimization asks whether AI can find a rental company, but operators also need to know whether the agent inspected enough of the market, compared equivalent offers, and presented a rate the traveler can actually book. (Part 1 of 2)
Read More →