

Brazil’s Car Rental Industry Faces a Pivotal 2026
Structural pressures and opportunities converge to prompt rental car operations to find new balances between revenue and resales.
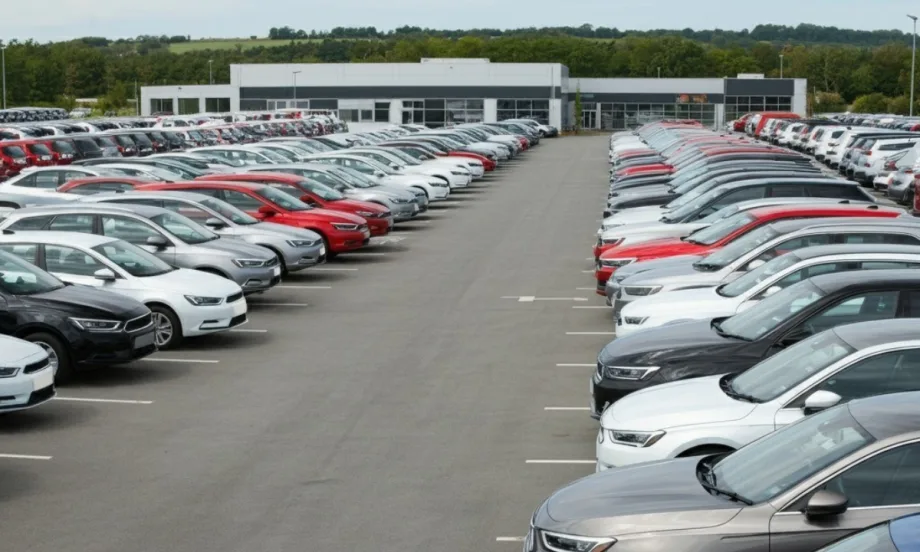
A CarShop auto dealership that sells rental cars in Mato Grosso, a state located in the Central-West region of Brazil.
Photo: Julian Gritsch / JG Corp.
- Companies must balance generating revenue with optimizing vehicle resale strategies.
- Industry shifts present both challenges and opportunities for rental operations.
*Summarized by AI
Brazil’s car rental industry is entering 2026 at a rare inflection point, where macroeconomic forces, technological disruption, and shifting consumer behavior are converging simultaneously.
This is not a cyclical slowdown or short-term correction. It is a structural recalibration.
For decades, Brazilian operators have built resilient business models in one of the world’s most complex operating environments. High interest rates, layered taxation, and volatile residual values forced companies to master the balance between rental revenue and vehicle resale.
That equilibrium, however, is now under increasing strain.
Chinese Automakers Reshape Fleet Risk
One of the most visible forces comes from China. Chinese brands now account for more than 80% of electric vehicle sales in Brazil, signaling a fundamental shift in consumer perception.
Meanwhile, manufacturers such as BYD are investing heavily in local production, committing more than $5.5 billion to Brazilian operations and projecting annual capacity of up to 600,000 vehicles.
This level of scale changes fleet economics across the industry. Faster product cycles, aggressive pricing strategies, and rapid technological evolution are compressing the predictability of residual value.
For rental operators, this is not merely a purchasing challenge. It directly affects depreciation models that were built for a slower, more stable vehicle lifecycle.
In a market where innovation accelerates and prices adjust quickly, historical resale behavior is no longer a reliable anchor.
Tax Reform Removes Legacy Buffers
Brazil’s long-anticipated tax reform adds another layer of complexity. While designed to simplify the system, the reform also removes many of the structural buffers that previously absorbed operational inefficiencies.
The critical question for operators is no longer whether taxes will rise or fall, but whether their business models can perform in a more neutral environment.
Companies that depend on intricate tax engineering between rental operations and vehicle disposal will face greater exposure, while those with clarity on value creation may benefit from increased transparency.
Capital Costs Remain a Defining Constraint
Unlike the U.S. or China, Brazil continues to operate under structurally high capital costs.
Expensive credit limits the speed of fleet renewal, increases sensitivity to depreciation errors, and magnifies the consequences of misaligned pricing decisions.
Despite the availability of financing, lenders and investors are becoming more selective. Credit is increasingly tied to data-driven risk models, asset performance, and governance rather than sheer fleet scale.
Technology Becomes a Strategic Divider
Technology is emerging as a decisive competitive factor.
Brazilian operators are accelerating their adoption of automation, telematics, and artificial intelligence, particularly agent-based AI systems that support fleet planning, pricing optimization, risk analysis, and customer service. These tools are reshaping operational efficiency, cost control, and decision-making speed.
But technology alone is not enough.
The biggest challenge is no longer access to tools but preparing people to work alongside them. AI, automation, and data-driven decision-making change how companies operate, but without training and cultural adaptation, they don’t translate into better results.
Talent development, process redesign, and internal alignment are now as critical as software deployment.
Elections and World Cup Add Demand
Against such numerous industry influences, 2026 will be shaped by two major external events: Brazil’s national elections and the FIFA World Cup.
Elections introduce uncertainty but often stimulate short-term economic activity, infrastructure spending, and regional mobility. The World Cup, hosted across North America, is expected to boost international and domestic travel flows and increase rental car demand, especially in tourism-driven regions.
For Brazilian operators, these events present an opportunity, but also a risk. Demand spikes can multiply the consequences of fleet misalignment, pricing errors, or contractual rigidity if not managed carefully.
A Selective, Not Pessimistic, Outlook
Despite the pressures, the outlook for Brazil’s car rental industry in 2026 is more selective instead of pessimistic.
Rental fleet operators can position themselves to strengthen their businesses if focus on three key approaches:
Treat fleet as a portfolio of risk rather than inventory.
Align depreciation, pricing, and contracts as interconnected decisions.
Invest in both technology and people are well positioned to emerge stronger.
Scale needs to be combined with flexibility to adapt to this shifting environment and define success.
Brazil cannot simply replicate the efficiency-driven U.S. model, nor ignore China’s industrial logic. It must build its own path, shaped by expensive capital, faster innovation cycles, tax reform, and more sophisticated technology.
Those who recognize this early will choose how to adapt.
Those who delay will discover that the market can become very impatient.
More Rental Operations
The Booking Is Confirmed, But Is Your Customer Ready to Drive?
For international renters, a confirmed reservation doesn’t always mean they’re eligible to drive. Earlier checks can help operators catch documentation and payment issues before the customer reaches the counter.
Read More →
ICRS 2027 Opens Call for Papers
The International Car Rental Show seeks session proposals on the business, operational, and technology issues facing car rental operators. Submissions are due Jan. 15.
Read More →
Turo to Launch Vehicle Delivery Service
Turo Delivered will let travelers search for vehicles that hosts can deliver directly to hotels, homes, airports, train stations, and other locations.
Read More →
Palm Beach Airport Code Change Creates Car Rental Distribution Gap
A test of rental searches under the old PBI and new DJT airport codes returned largely different sets of brands and vehicles, highlighting a potential distribution problem for rental operators.
Read More →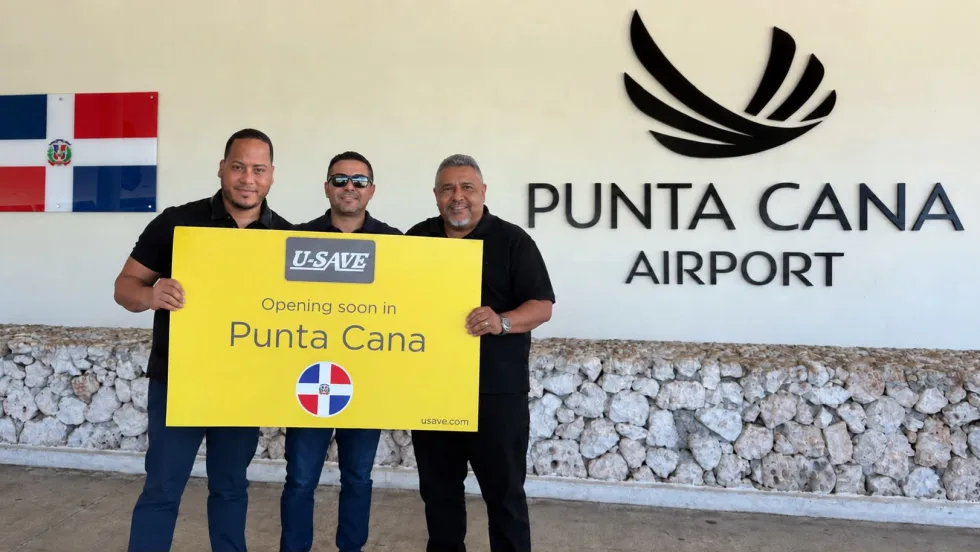
U-Save Continues Dominican Republic Expansion with Launch in Punta Cana
The new franchise location builds on U-Save’s existing Santo Domingo operation and will begin taking reservations for October 2026.
Read More →
When AI Books the Rental Car, Who Controls the Sale?
As AI moves from comparing rental rates to completing transactions, operators need to understand how travelers find, interpret, rank, and ultimately see their offers. (Part 2 of 2.)
Read More →
European Booked Car Rental Rates Fell 5%, Results Varied by Country
Ireland, Cyprus, and the United Kingdom saw steep declines, while booked rates rose in Poland and Hungary.
Read More →
Is It Time to Rethink Rental Categories?
As traditional economy and compact cars disappear from the market, longtime rental operator Mike DeLorenzo asks whether the industry’s familiar vehicle categories still make sense — and what operators need to rethink along with them.
Read More →
Who Owns the Rate? AI Is Creating a New Distribution Problem for Car Rental
Generative Engine Optimization asks whether AI can find a rental company, but operators also need to know whether the agent inspected enough of the market, compared equivalent offers, and presented a rate the traveler can actually book. (Part 1 of 2)
Read More →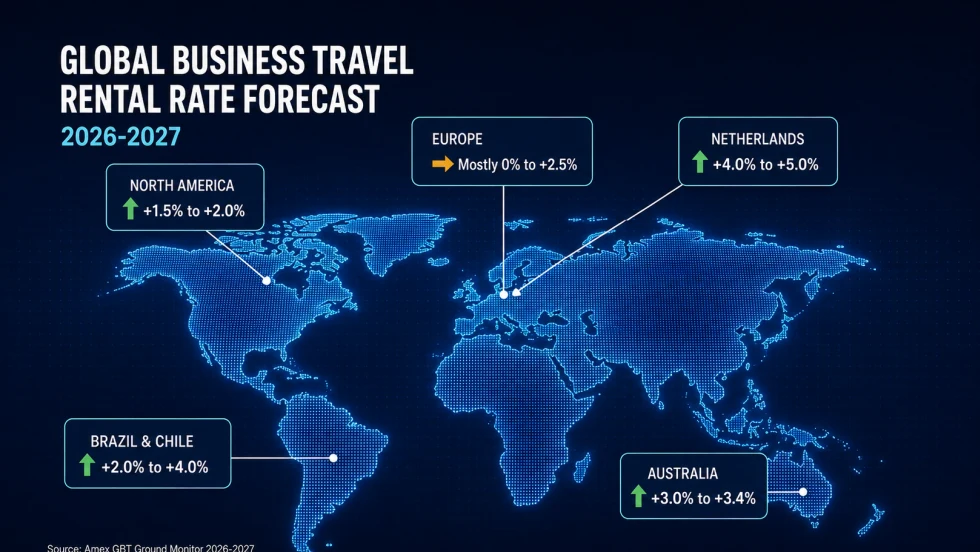
U.S. Business Travel Car Rental Rates Forecast to Rise Up to 2%
Improved fleet supply should limit pricing gains in 2026-27, while insurance, repair costs, and softer residual values continue to pressure rental operations, according to Amex GBT.
Read More →